Starting a new company
Check your proposed capital before incorporating or transferring funds.

Does Japan require ¥30 million to obtain a Business Manager visa? Under the revised rules effective October 16, 2025, qualifying business scale is a central requirement. However, the amount is calculated differently for a corporation and a sole proprietor. We help overseas founders and existing business owners understand what counts, what does not count, the documents required and how the rule affects their residence applications.
Check your proposed capital before incorporating or transferring funds.
Review registered capital, share acquisition, financial statements and possible capital increases.
Understand renewal treatment and the October 2028 transition without assuming automatic refusal.
The revised Business Manager criteria generally require assets used for the business with a qualifying total of at least ¥30,000,000. For a corporate business, the Immigration Services Agency explains that this normally means the company's paid-in share capital or total contributions, according to the legal form. For a sole proprietor, the authority considers the qualifying total actually invested in the operation.
| Business form | How the ¥30 million standard is assessed | Evidence to consider |
|---|---|---|
| Kabushiki Kaisha (KK) | Generally its qualifying paid-in share capital (shihonkin), rather than the value of all business assets or revenue. | Commercial register, balance sheet, share issuance and payment records. |
| Godo Kaisha (GK) | Generally the qualifying total of capital contributions (shusshi no sogaku). | Registration, articles or member-contribution records, financial statements and supporting payments. |
| Other relevant corporate forms | Relevant capital or total contributions according to the legal form and Immigration Services Agency guidance. | Corporate registry, capital records and supporting financial evidence. |
| Sole proprietor | Qualifying amounts actually invested in the business, such as securing premises, one year's staff salaries and equipment expenditures. | Financial statements, contracts, payroll, receipts, transfers and other proof of actual investment. |
In particular, a company with considerable business assets, sales or retained profits does not necessarily satisfy the corporate capital test. The legal classification and supporting records are important.
For corporations, the Immigration Services Agency explicitly distinguishes qualifying corporate capital from other accounting items. The following examples help identify mistakes before filing.
| Amount or item | Corporate capital test | Practical explanation |
|---|---|---|
| Paid-in share capital of a KK | Generally counts | Check the actual registered capital and supporting corporate records. |
| Total capital contributions of a GK | Generally counts | Check the company's contribution records and applicable legal definition. |
| Capital reserve / surplus | Does not simply count | Official Q&A excludes capital reserve and capital surplus from the corporate figure. |
| Retained earnings | Does not simply count | Accumulated profits cannot be added directly to the corporation's qualifying capital. |
| Office rent and employee wages | Cannot be added for a company | The corporation cannot combine these operating costs with paid-in capital to reach the threshold. |
| Inventory, equipment or property value | Not automatically countable | Ownership or spending does not by itself replace the company's prescribed capital figure. |
| Annual sales or forecast revenue | Not the relevant capital figure | Turnover and expected future income are different from paid-in capital or contributions. |
| Personal savings or a shareholder loan | Not automatically countable | The financing source and corporate accounting treatment must be reviewed; debt alone is not paid-in capital. |
Immigration may examine the company register and balance sheet as well as records demonstrating the actual financing arrangements. Even when the first accounting year has not ended, official Q&A states that a balance sheet as of incorporation or another appropriate point should be prepared.
Not enough on those figures alone. Retained profits are not directly added to the company's capital for this test.
Not enough by addition. Operating expenses do not top up the corporate capital figure.
Potentially meets the scale figure. Other immigration conditions must still be satisfied.
Different calculation. Qualifying actual premises, employee and equipment expenditures may be assessed together.
Cannot simply combine them. Official Q&A requires at least one of the relevant companies to reach the ¥30m capital threshold.
Needs individual review. Purchase price paid to another shareholder is distinct from the company's own capital, and management must be genuine.
A genuine increase in capital can affect the corporate scale calculation if properly implemented and documented. However, corporate accounting and registration must reflect the actual transaction. A founder should coordinate legal, accounting and immigration planning before transferring large amounts of money.
Review the corporate resolutions, payment evidence, revised registration and the updated balance sheet.
Confirm the target company's registered capital and actual operations. The purchase price is not automatically new company capital.
Some paid stock-acquisition-right arrangements may receive special treatment under detailed ISA guidance; they require specific conditions and evidence.
Company commercial-registration work must be handled through the appropriate authorized professional. Tax or accounting advice is separate from immigration application support.
Generally, yes. The revised rules require both qualifying business scale and at least one specified full-time employee. They also address Japanese-language ability, the applicant's degree or business-management experience, a suitable office, a credible business plan and necessary business permits.
| Condition | General rule to examine |
|---|---|
| At least one full-time employee | Qualifying headcount generally includes Japanese nationals, Special Permanent Residents and specified status-based foreign residents. Most activity-based work-visa holders do not count for this particular requirement. |
| Japanese-language ability | The applicant or an eligible full-time employee must meet the specified B2-equivalent standard through accepted evidence. The eligible group for this language test differs from the headcount test. |
| Management background | Relevant master's-level or higher qualification, or normally at least three years of qualifying business management experience. |
| Japanese business office | Genuine, suitable premises. A home shared as an office is generally not accepted under the revised approach. |
| Business plan | Credible activities and finances, with review by a designated qualified professional where required. |
| Actual managerial role | Substantive decisions and participation in operations; a nominal director position is not sufficient. |
For qualifying people already holding Business Manager residence status under the former rules, the Immigration Services Agency established transitional treatment following the reform. Renewals filed during the first three years after October 16, 2025 are not refused solely because the new standard has not yet been met. The authorities also examine business performance, compliance and prospects of satisfying the revised rules.
| Application situation | What the official guidance explains |
|---|---|
| Existing eligible resident, transitional-period renewal | Failure to meet the revised capital threshold alone is not an automatic refusal. Financial results, legal compliance and improvement plans remain important. |
| Renewal filed after the transition | Revised criteria generally apply. Even where they are not yet fully met, good business performance, proper tax compliance and a credible prospect of meeting the criteria by the next renewal may be considered in a comprehensive assessment. |
| New COE or change-of-status application | Normally examined against the revised criteria, unless a specific transitional or special regime applies. |
New COE from overseas, change inside Japan or renewal of an existing Business Manager residence status.
KK, GK, sole proprietorship or acquisition. Identify the correct capital or investment calculation.
Compare registration, balance sheet, contribution records, expenditure records and any proposed capital increase.
Review full-time staff, Japanese, managerial background, premises, plan, permits and real activities.
Identify missing proof and coordinate with the necessary company registration or accounting professionals.
Prepare the appropriate application within our authorized scope, subject to an agreed fee and individual assessment.
Tell us your company type, registered capital or contributions, current residence situation and whether you are planning a new application or renewal. We can identify which records require attention before you invest further.
Ask About Your Capital and Visa Options| Service | Professional fee (tax included) | What is covered |
|---|---|---|
| Business Manager COE application | From ¥165,000 | Immigration application documents and authorized submission assistance. |
| Change of Status to Business Manager | From ¥165,000 | Change-of-status application and supporting evidence. |
| Standard Business Manager renewal | From ¥66,000 | Ordinary extension with no major changes; complex cases separately quoted. |
| Company formation documentation support | From ¥110,000 | Separate work relating to formation documents, not including commercial registration or the immigration filing. |
These are starting professional fees, not a combined package. Immigration permission charges where applicable, translations, certificates, postage, travel and independent business-plan reviews may be additional. Company registration, accounting and tax filings must be arranged through appropriately authorized professionals. We provide a quotation before paid work begins.
Not as a universal personal bank balance requirement. For a corporation, the relevant measure is normally the company's paid-in capital or total contributions. Your personal contribution, source of funding and genuine managerial role can also require examination.
Not for an ordinary new Business Manager application under the revised standards effective October 16, 2025. Specific earlier applications or special arrangements must be reviewed individually.
No. Annual turnover is different from the qualifying capital or investment calculation. A company with high sales but insufficient prescribed capital may not meet this requirement.
Under the Immigration Services Agency's official Q&A, capital reserve, capital surplus and retained earnings are not simply included in the corporation's relevant capital figure. A valid corporate transaction changing capital would need separate examination.
No. The Agency expressly explains that corporations cannot add rent or wages to paid-in capital or total contributions to make up the ¥30 million. Sole proprietors use a different qualifying investment calculation.
There is no corporate share capital. The relevant total may include qualifying amounts actually invested in securing business premises, one year's employee wages and equipment, supported by financial statements, contracts, payment records and receipts.
Not simply. Official guidance says that where management involves multiple companies, at least one must meet the relevant ¥30 million capital threshold.
The official Q&A calls for a balance sheet at incorporation or another appropriate point even when the first financial year has not ended.
Not automatically. A share purchase price paid to an existing shareholder is not the same as the target company increasing its registered capital. The company's scale and your actual management duties must be verified.
A loan or debt balance is not automatically qualifying corporate capital. The financing structure, legal contributions and accounting treatment require individual review. Do not relabel debt as capital without an actual lawful transaction.
Yes, the Immigration Services Agency explains that the capital/business-scale requirement also applies when the applicant will engage in management as a manager. Ownership and actual management activity are separate issues.
Generally yes, at least one qualifying full-time employee is a separate condition. The permitted categories include Japanese nationals and specified status-based foreign residents; an ordinary activity-based work visa does not automatically meet the headcount requirement.
Not merely because of the capital amount. The applicant must engage in genuine business operation or management, with the other immigration requirements satisfied. Passive investment alone is not enough.
Not automatically. Qualifying existing residents have transitional treatment, and even after the transition the official Q&A describes comprehensive review in particular circumstances. Business activity, tax compliance and a realistic improvement plan matter.
No automatic departure rule follows merely from that number. The Immigration Services Agency expressly rejects this interpretation, while explaining that renewal decisions depend on the full circumstances and are never guaranteed.
Our Business Manager COE and change-of-status professional fees start from ¥165,000 (tax included). Standard renewal starts from ¥66,000 (tax included). The ¥30 million business-scale threshold is unrelated to our professional fees.
Based in Sagae, Yamagata Prefecture, we assist foreign entrepreneurs and companies in Japan and overseas with Business Manager immigration applications and supporting documents. We can review the relevant capital or business investment evidence and coordinate with other professionals when separate registration, tax or accounting services are necessary.
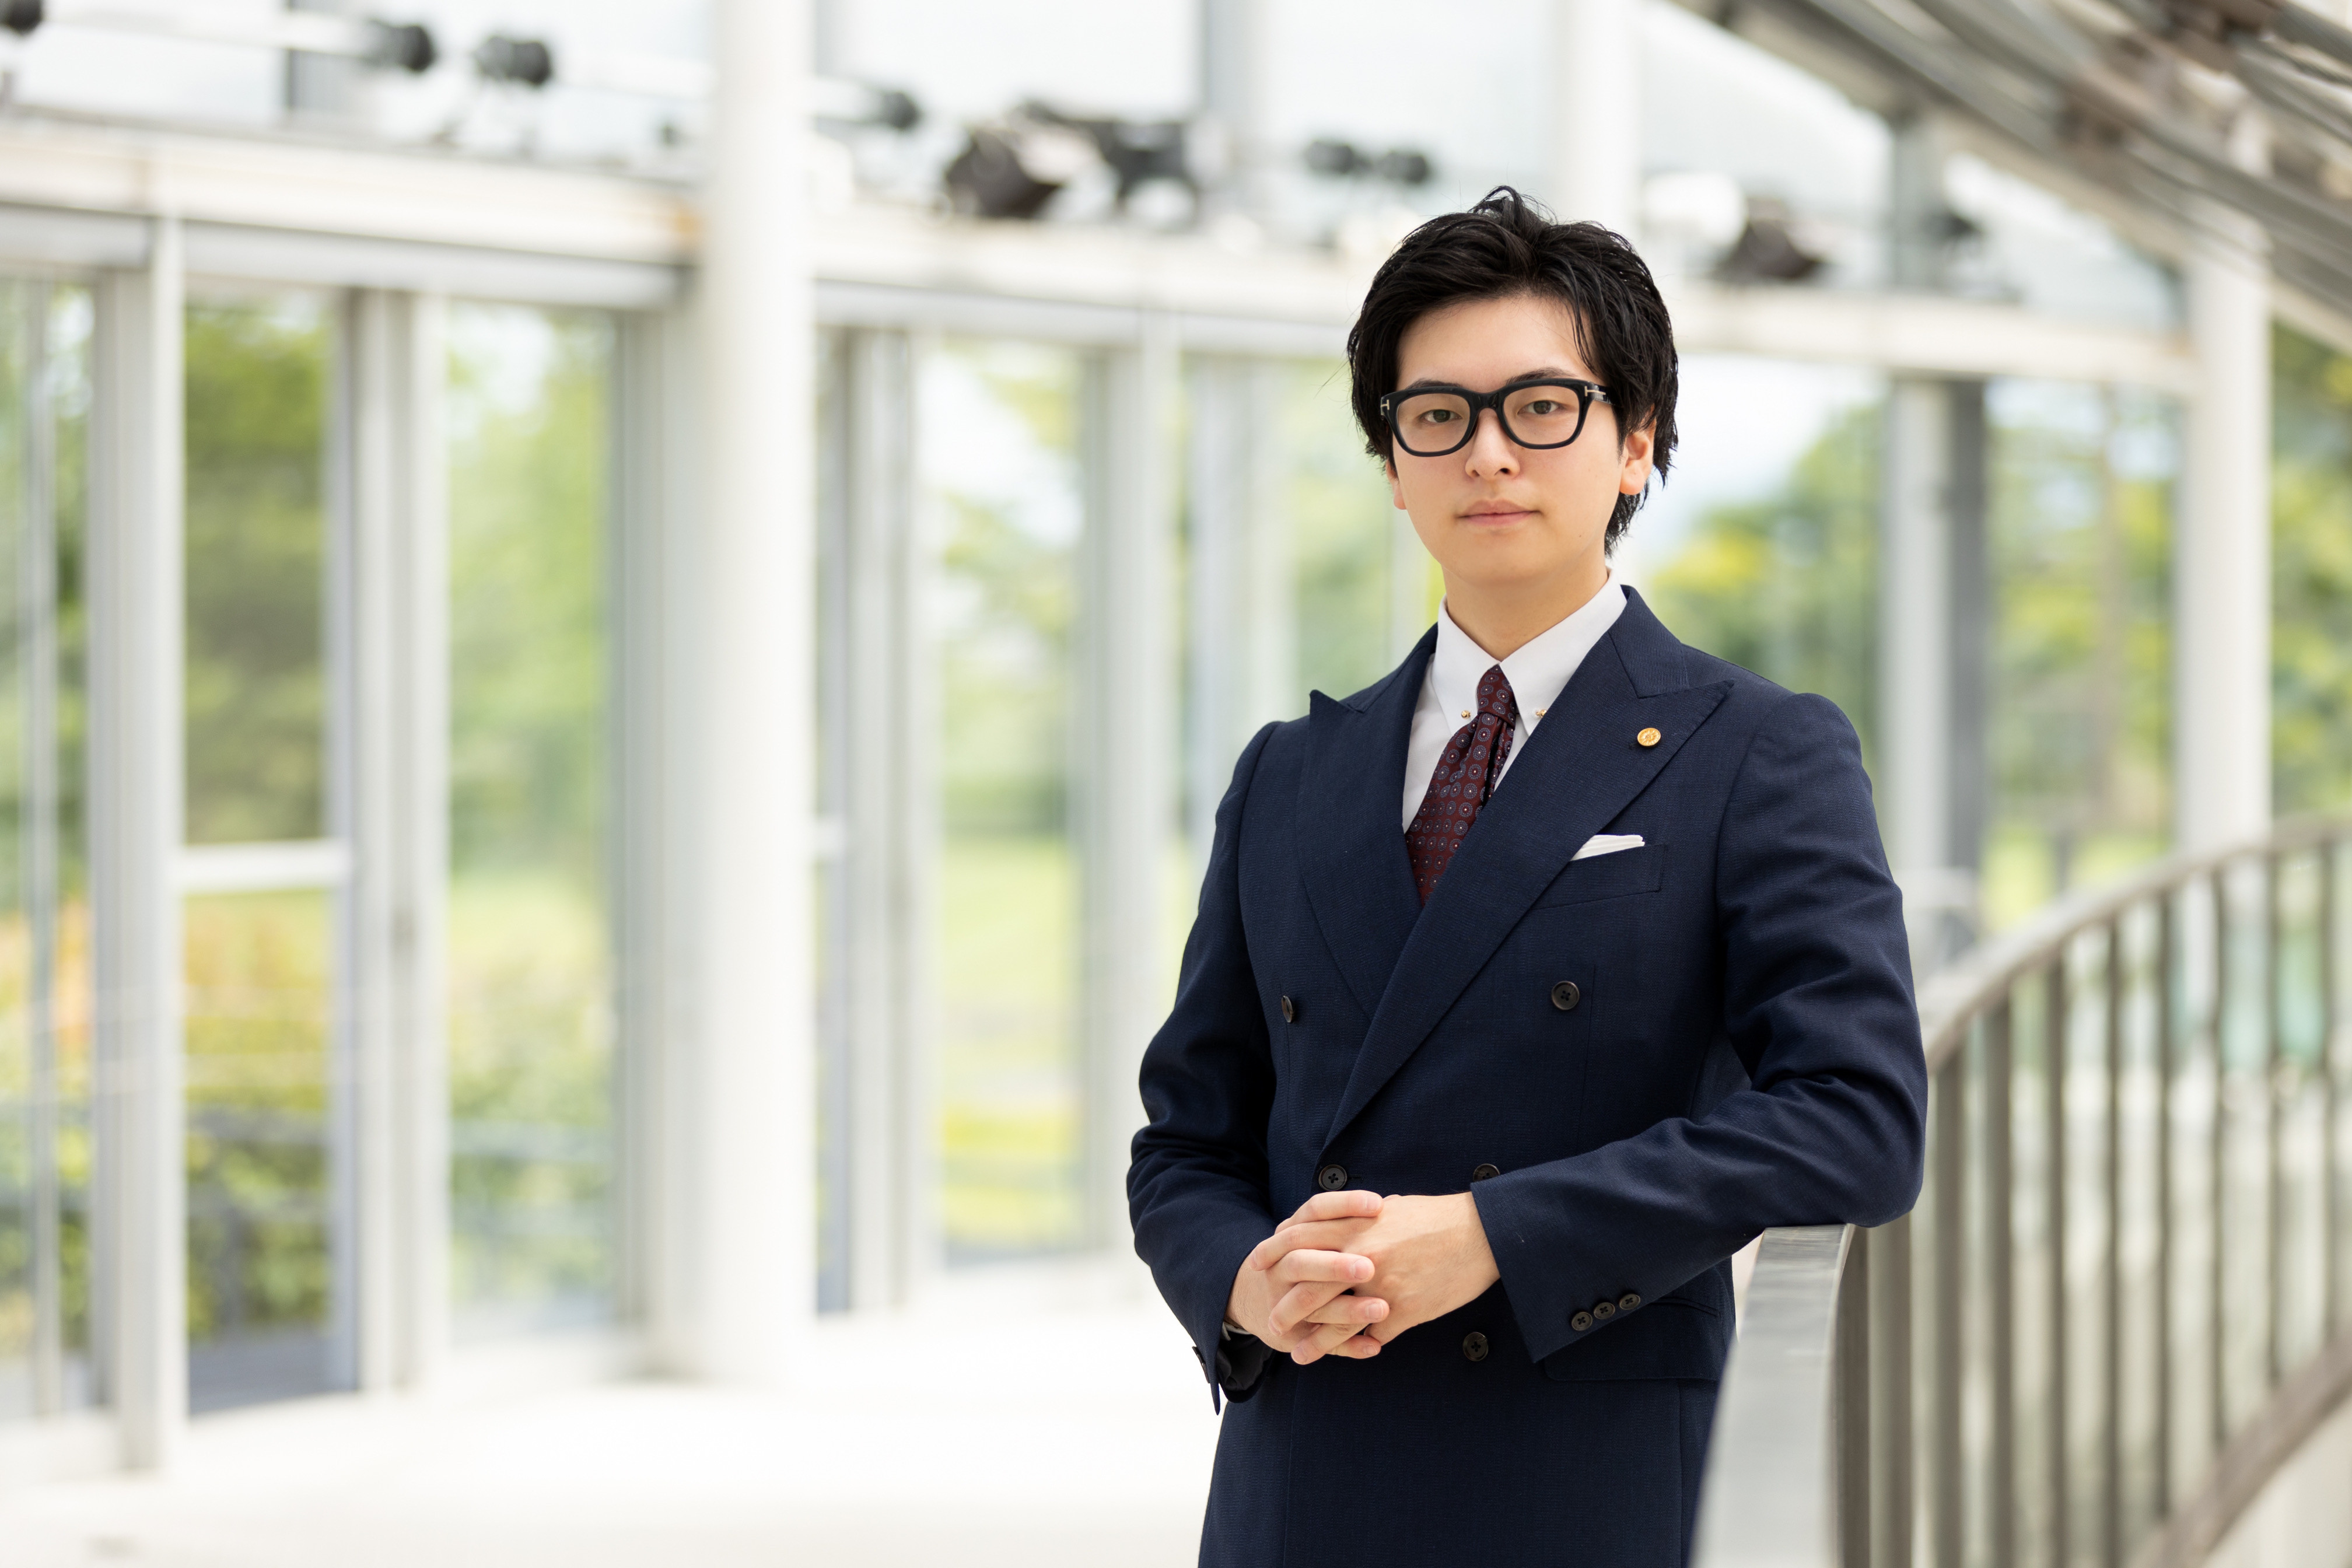
Licensed Administrative Scrivener / Immigration Application Intermediary
Kawagoe Masanobu Administrative Scrivener Office
Sagae, Yamagata, Japan
English enquiries welcome. Procedures, service scope and filing arrangements are reviewed for each case.
The authority's detailed Q&A clarifies which amounts count, how a sole proprietor is treated, the evidence required and the transitional treatment for renewals. Official requirements and submission forms should be checked for each application.
Tell us whether your business is a KK, GK or sole proprietorship, the capital or qualifying investment you can document, your staffing and current immigration situation. We will explain the relevant evidence, application options and professional fees before engagement. Residence permission cannot be guaranteed.
Telephone 9:00–18:00 JST · COE/change support from ¥165,000 (tax included) · English enquiries welcome worldwide